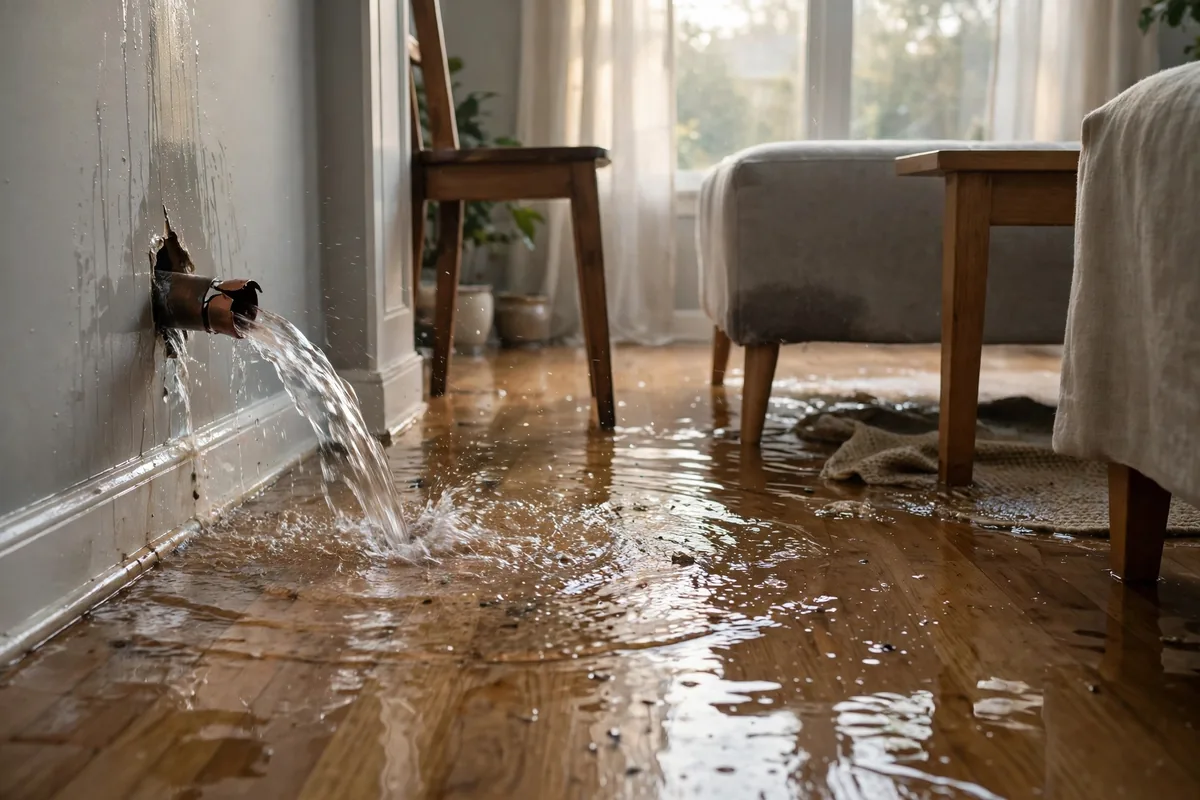
What Happens If Your Pipes Burst
What Happens If Your Pipes Burst? An Hour-By-Hour Damage Timeline
Questions on what happens if your pipes burst? One free call connects you with a local pro who can arrive in 30–60 minutes. Call now for help.
Answered 24/7 · Free To Call · No Obligation
Free Call · Answered 24/7 · Local Pros Near You
A burst pipe insurance claim is documented in the first hours or reconstructed painfully later. The record that works: dated photos and video of the source and the damage before cleanup, the water meter reading, the cut-out pipe section kept as physical evidence, the pro's written finding of what failed and why, a timeline of your calls and actions, and receipts for every mitigation step. Photograph first, mop second — the evidence is perishable and the water is not.
Nobody plans the documentation of the worst evening of their plumbing's life, which is why claims so often rest on three blurry photos and a memory. It does not have to be that way: the evidence an insurer needs is exactly the evidence a careful homeowner naturally creates in the first hours — if the camera comes out before the mop. This guide is the checklist version, in the order events actually happen.
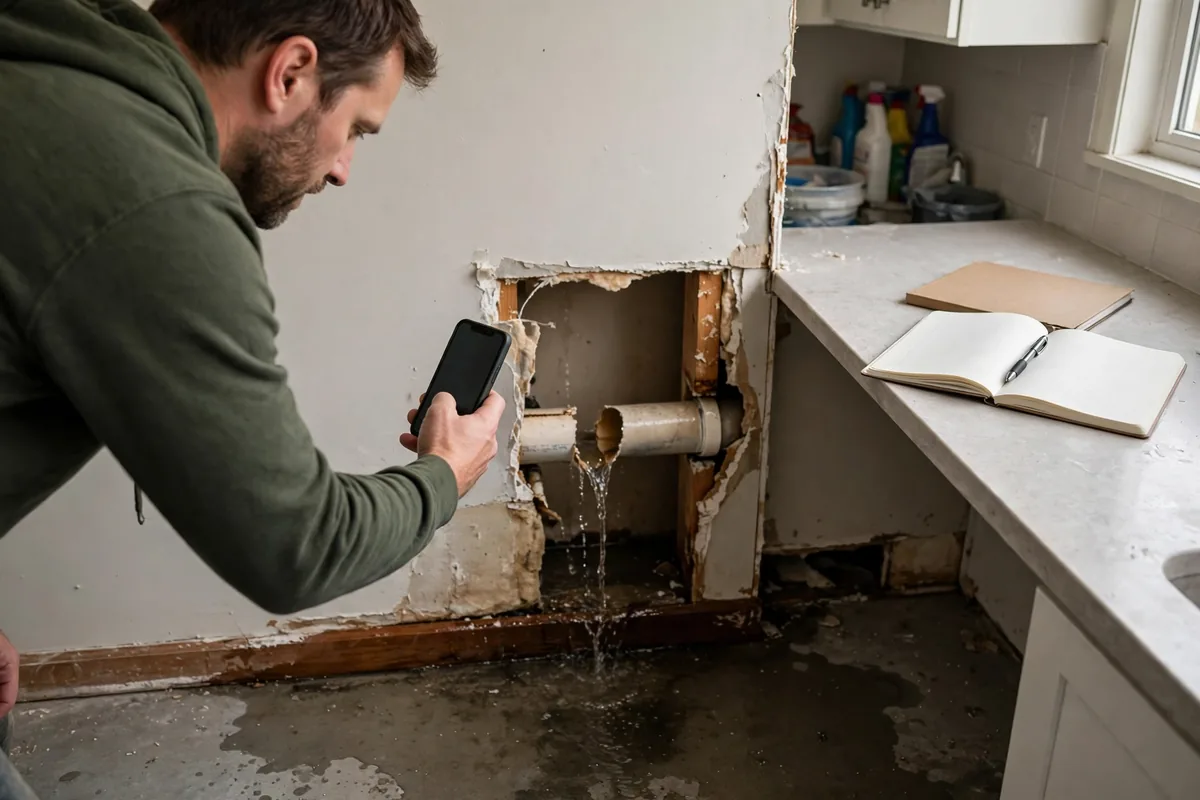
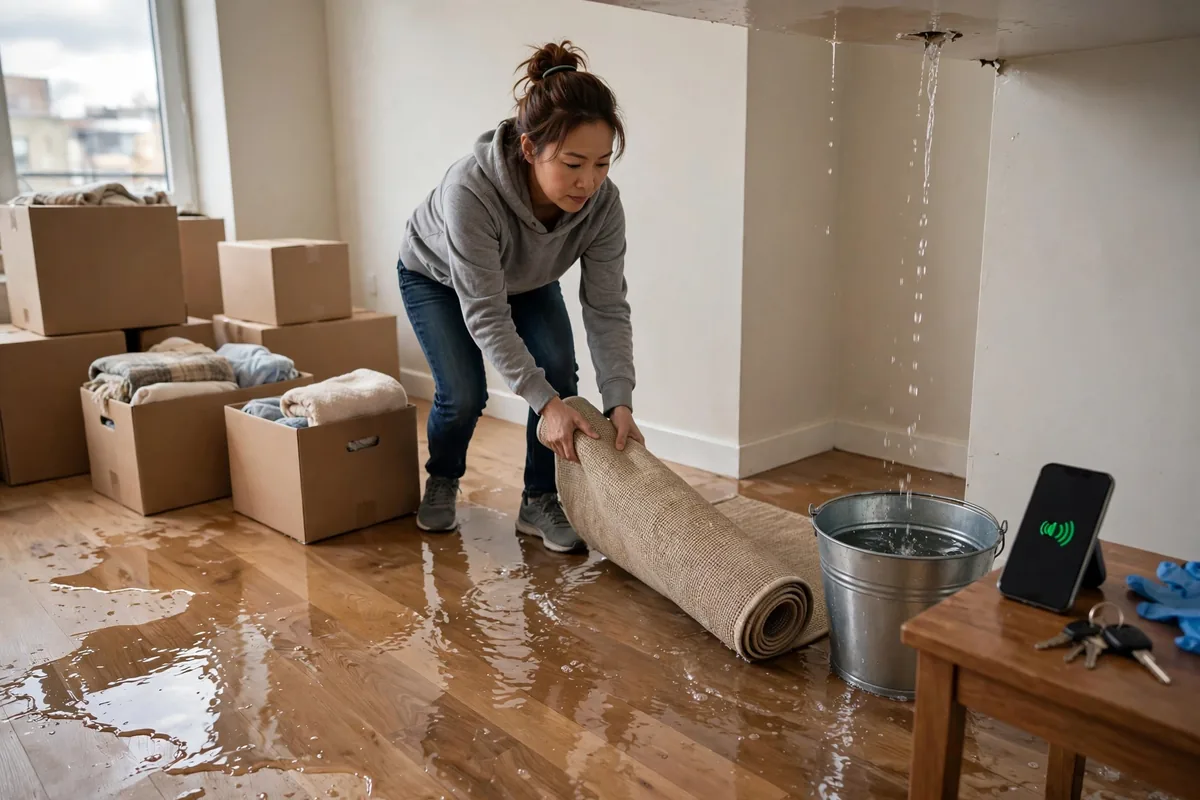
Start wide, then go close. Wide shots of every affected room showing the water's extent, down to the basement and the crawl space if the water travelled; then the source — the split pipe itself, ideally with water still escaping or freshly stopped; then each damaged material and item in place: flooring, skirting, cabinetry, belongings where they sat. Add the water meter reading and the shut-off valve position. Shoot a slow video walk-through narrating the time and what you are seeing; narration timestamps your account in your own words.
Order matters because cleanup destroys sequence. The photograph of the soaked rug in place is evidence; the same rug in the garden is an assertion. In Akron, OH and everywhere else, adjusters consistently say the same thing: the claims that settle smoothly were photographed before they were tidied.
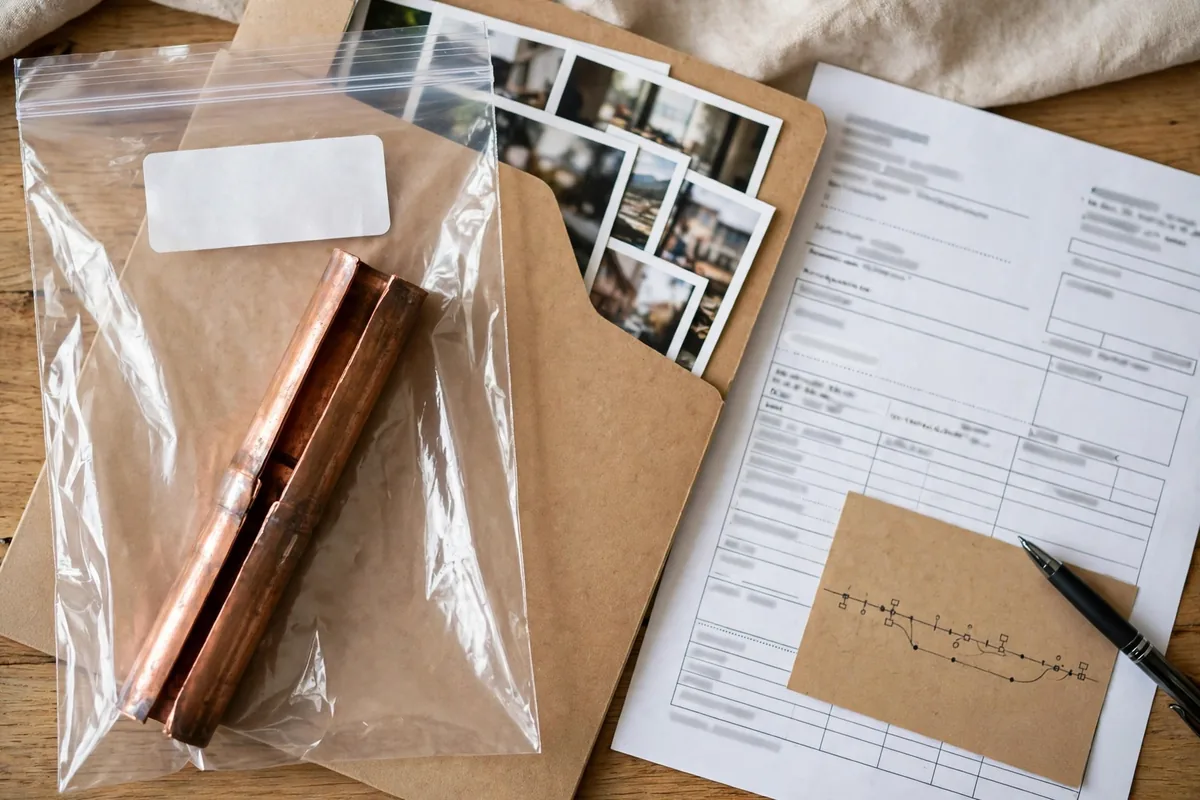
Because it is the cause, in physical form. The split section shows what failed — a freeze split's lengthwise tear, corrosion's pinhole in thinned metal, a fitting's crack — and it corroborates the pro's written finding better than any description. Insurers distinguish sudden failures from slow, known deterioration, and the cut-out is exhibit A in that distinction: a clean split in sound pipe tells a sudden story; a section crusted with long-term scale tells another, and honesty about which one you have is the foundation of a credible claim.
Ask the pro to leave it with you, bagged, with the date written on the bag. It costs nothing and it cannot be recreated later — once the repair is in and the old pipe is in a skip, the physical story of your claim is gone. Keep it with the paperwork until the claim is fully closed.
Three documents carry the claim. First, the timeline: when you discovered it, when the water was shut off, who you called and when, when the pro arrived — written the same day, while memory is exact. Second, the pro's written finding: what failed, where, the apparent cause, and the repair performed, on their invoice or report. Third, the inventory: a room-by-room list of damaged items with approximate ages and what happened to them.
Notify the insurer early — many policies expect prompt notice of water damage — and log that call too. Your state department of insurance publishes plain-language guidance on how claims proceed in your state; in Ohio and Texas alike, that office is the free, neutral explainer when any step confuses you.
Memory fades in a week. A dated photo, a written finding and a bagged piece of pipe are still telling the same story in six months — that is what documentation means.
Water Moving Where It Shouldn't?
One free call connects you with a local pro who can arrive in 30–60 minutes and find the burst without tearing the house apart first.
Call (800) 555-0100Mitigation — the steps that stop damage growing — is both a policy expectation and a documentation subject. Photograph the drying setup: water extraction in progress, air movers and dehumidifiers placed, moisture meter readings on walls across the drying days, and the materials removed (with photos before removal). Keep every receipt: the pro's invoice, the drying company's, emergency purchases, a hotel if the home was uninhabitable.
This record does double duty. It shows the insurer you acted promptly — which their assessment of the damage total quietly assumes — and it shows the drying was verified rather than assumed. The structural drying log belongs in the same folder, beside the thermal imaging camera sweep and any pipe camera inspection report from the diagnosis stage; diagnostic evidence is claim evidence.
An adjuster's visit goes well when the file is already built: the photo set in chronological order, the timeline, the pro's finding, the inventory, the receipts, and the cut-out section available to inspect. Walk them through in event order. If areas have been repaired or dried, your photos carry those rooms' stories. If something cannot be shown — a discarded item, a dried wall — say so plainly and show the photo instead.
Keep the exchange factual and keep your own notes of it: who came, when, what was said, what happens next and by when. In Austin, TX, where slab bursts complicate the damage picture, homeowners find the under-floor evidence — the acoustic leak detection report, the located position marked on the concrete slab — particularly valuable in this conversation, because the adjuster cannot see under a floor either.
Cleaning everything before photographing. Throwing the failed pipe away with the debris. Waiting days to notify. Discarding damaged belongings before they are recorded. Starting permanent repairs before the damage is documented, where documentation was still possible. And the subtle one: describing the event loosely — "the pipe has been leaking for months" said casually about a sudden burst reframes the event as deterioration. Describe precisely what happened, when you knew, and what you did; precision is not spin, it is accuracy.
None of this requires legal knowledge — it requires a phone, a notebook and the discipline to use them before the mop. Add one calm-day habit and the file builds itself next time: keep your insurer's claim number and your pro's number saved, and know where the main shut-off valve is. In Addison, IL, the households whose claims closed fastest after winter bursts were, without exception, the ones who could hand over a folder.
The repair itself is deliberately plain: a section replacement joined with a pipe coupling, a press fitting or a push-fit fitting, a pipe repair clamp only as a stopgap, soldering where copper is joined, and a full pressure test before anything is closed up.
More straight answers about finding hidden bursts and what happens after you find one.
Still Have Questions? Call Free
A real person answers, day or night, and connects you with a local pro who can check the problem in person.
(800) 555-0100As soon as the emergency is controlled — the same day where possible. Policies commonly require prompt notice of water damage, and early notice starts the clock on their side too: claim number issued, adjuster assigned, guidance given on what they need. The call is short and does not commit you to anything beyond reporting the event; have your timeline notes in front of you so the account you give is the accurate one.
Commonly, policies respond to the sudden water damage the burst causes — soaked structure and belongings — while the failed pipe's own repair is often treated as a maintenance item and handled differently or excluded. The exact split lives in your policy wording, and your state department of insurance explains the general rules for your state. This is another reason the finding matters: it defines what was the event and what was the damage.
Document the discovery exactly as it happened: when you returned, what you found, the meter reading, the state of rooms in the order you entered them — video first, before touching anything beyond the shut-off. Policies often examine precautions for empty homes (heating maintained, water off, checks arranged), so include whatever records show yours: thermostat settings, a neighbour's visits, your winterising steps. Honest, complete records are the whole strategy.
Mitigate fully; renovate cautiously. Stopping water, drying, and removing sodden material that would grow mould are expected immediately and should be photographed as you go. Permanent restoration — new flooring, rebuilt cabinets — is normally sequenced after the damage has been recorded and assessed. If a repair cannot wait, document the area exhaustively first: photos, video, measurements, and the pro's written description of what was there.
Build the file from what exists: the pro's invoice and finding (request a copy with the diagnosis in writing), your call logs and messages showing the timeline, meter readings, receipts, and photos of the current state including any materials not yet repaired. Say plainly that the night photos were not taken. A candid, well-assembled file still outperforms a padded one — adjusters calibrate credibility quickly, and the pro's documentation often covers the gap.
Item, room, approximate age, and what the water did to it — a line each is enough. Photograph groups of items before disposal and keep anything the adjuster may want to see until told otherwise. For high-value items, any proof of purchase or photos of them in place before the event (old room photos count) strengthen the line. The list's power is completeness, not prose: the forgotten items are the ones that never get claimed.
It is often the document the claim turns on, because it converts 'a pipe burst' into a specific, dated, professional finding: component, location, failure mode, and the repair performed. A freeze split in sound pipe and a corrosion failure in end-of-life pipe are different stories to an insurer, and the report is where that distinction is established by someone who held the pipe. Always request the finding in writing, not just the invoice total.
The whole folder, for years: photos, timeline, findings, invoices, correspondence and the settlement. It proves the repair was done properly if you sell the home, answers questions if related damp appears later, and documents the home's maintenance history. The cut-out pipe can go once the claim is closed and any related work is complete — though many homeowners keep it as the story's souvenir in the garage.
Your state department of insurance is the free, neutral source: it publishes consumer guides to property claims and runs a helpline for exactly these questions, and the state attorney general — consumer protection office handles complaint patterns if you believe a company is acting unfairly. Neither replaces your policy wording, but both explain the landscape in plain language before you spend anything on advice.
Reviewed By Hamza
Lead Plumbing & Emergency Pipe Repair Specialist
Hamza is a certified plumbing and pipe restoration specialist with extensive field experience diagnosing sub-zero pipe splits, thermal stress fractures, and slab leaks across harsh winter climates. He specializes in non-destructive leak localization, copper-to-PEX conversions, and preventative freeze-proofing to safeguard residential and commercial plumbing systems against catastrophic water loss.
Updated October 30, 2026
Dealing with a fresh burst and want the finding documented properly from the first visit? One free call connects you with a local pro who can arrive in 30–60 minutes, stop the damage, and leave the written record your claim will need.
Free Call · Answered 24/7 · Local Pros Near You
Questions on what happens if your pipes burst? One free call connects you with a local pro who can arrive in 30–60 minutes. Call now for help.
Wondering about what do i do if a pipe bursts and what to do first? One free call connects you with a local pro who can arrive in 30–60 minutes. Call now.